Spending and Saving Responsibly
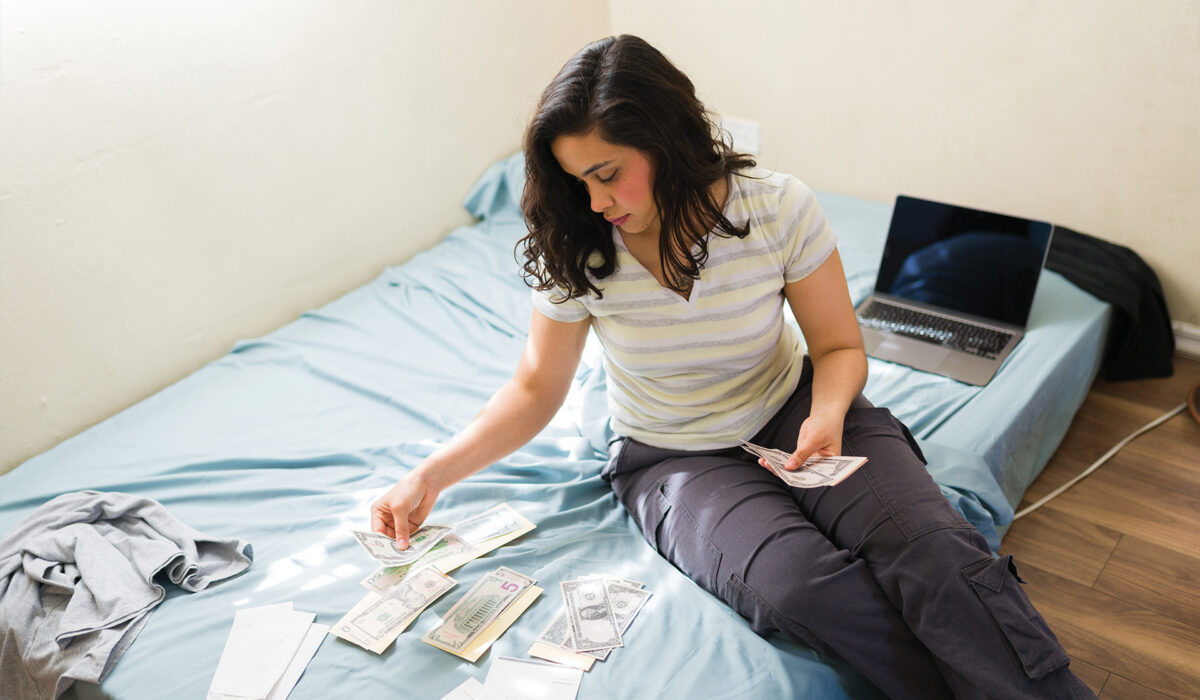
There are no loot boxes in real life.
The goal of a budget isn’t to restrict your life — it’s to make sure your money is doing what you want it to do, instead of disappearing without explanation.
The Lingo
Net income: Your take-home pay, aka, what lands in your bank account after taxes and deductions. This is your real number. Everything in your budget is built around it.
Fixed expenses: Bills that are the same every month: rent, renters insurance, a car payment, your phone plan. You know exactly what they’ll cost.
Variable expenses: Amounts that change month to month: groceries, gas, going out, clothing. These are harder to predict but easier to control.
Emergency fund: Money you save and do not touch unless something actually goes wrong. Start with a goal of $500, then build toward one month of expenses.
The Process
Step 1: Write down your net income. Look at your last few paychecks. If your hours vary, use the lowest recent paycheck as your baseline — it’s better to budget conservatively.
Step 2: List every fixed expense. Rent (your share), electricity, internet, phone and any recurring subscriptions like apps and streaming services. Add them up.
Step 3: Estimate your variable expenses. Go through your bank or card statements from the last month. What did you spend on food, transportation and everything else? Be honest. Most people underestimate this significantly.
Step 4: Subtract everything from your income. What’s left is what you have available for savings, fun and unexpected costs. If the number is negative, something has to change — either earn more, spend less or both.
The Habits
Check your accounts weekly. Start with five minutes on Sunday. You’re not doing math — you’re just staying aware of where you stand. Surprises are what blow budgets.
Give every dollar a job. Decide in advance how much you’re allocating to food, transportation, going out. When the money is gone, it’s gone.
Separate wants from needs. Be honest with yourself. Groceries are a need. DoorDash is a want. Both are fine — but calling wants needs is how budgets fall apart.
Build in a buffer. Leave $50 — $100 unallocated each month for things you forgot to plan for. Something always comes up.
The Method
The 50/30/20 budgeting rule is a simple starting framework for managing your income:
50% Needs: Rent, utilities, groceries, transportation.
30% Wants: Dining out, streaming services, entertainment, hobbies.
20% Savings: Savings and paying off debt.
With an entry-level income, the 50/30/20 rule won’t always be achievable. Treat it as a target direction, not a rigid rule. If you can only save 10% right now, that’s still real progress.
0 Comments